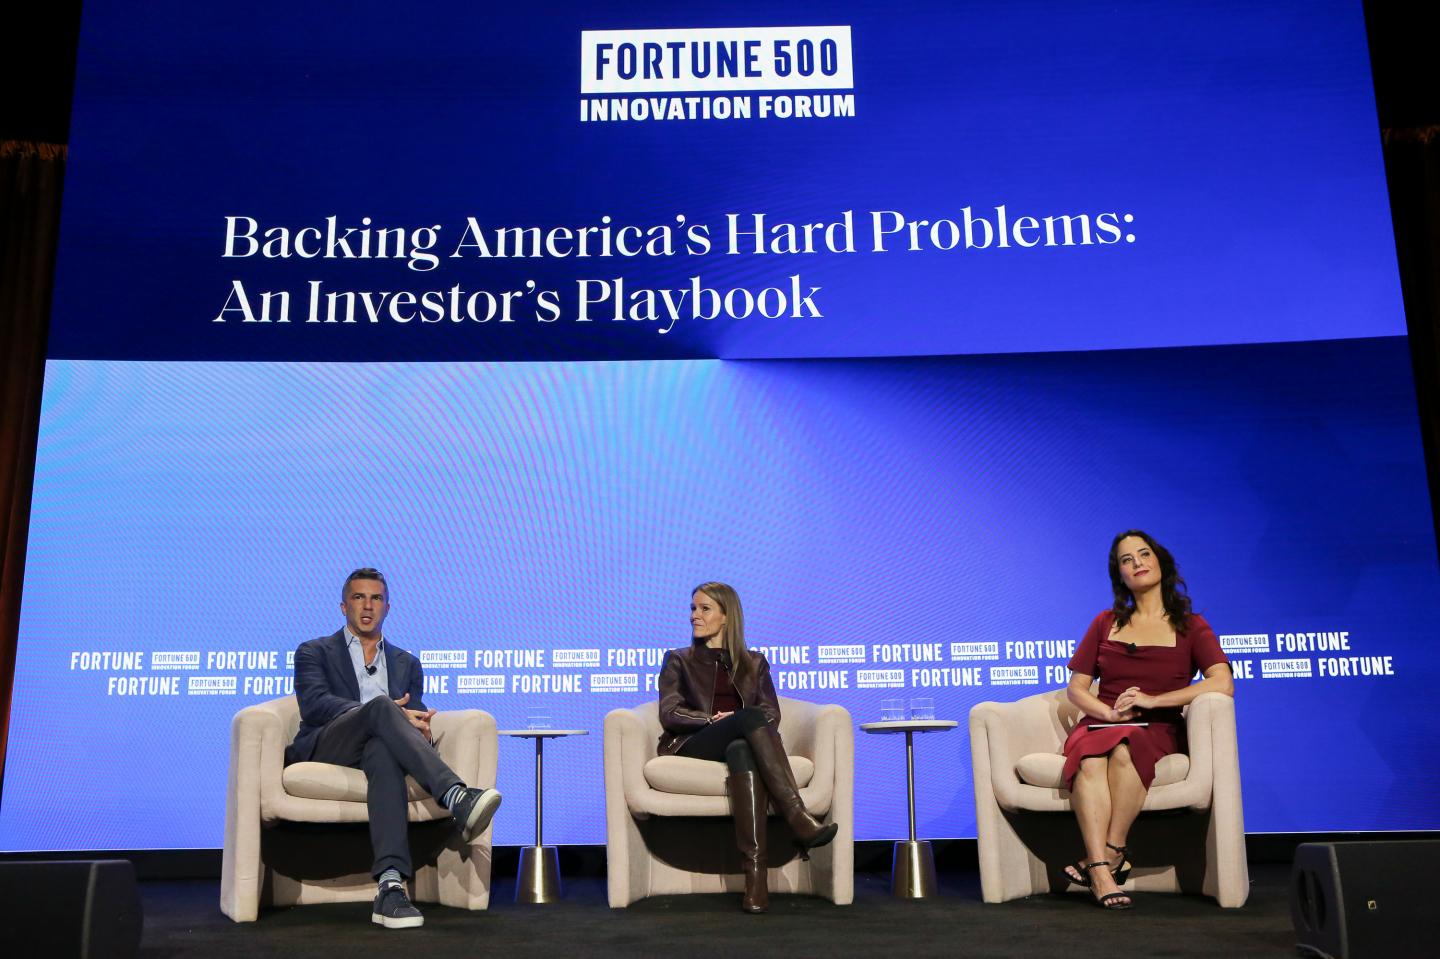
When it comes to defense tech, it’s a FOMO-YOLO market, two prominent investors in the sector said onstage this week at the Fortune 500 Innovation Forum in Detroit.
“I’m a long-term optimist and I’ve been doing this for 30 years, but I see activity in the capital markets that reminds me of 2021,” said Mina Faltas, founder and CEO of Washington Harbour Partners.
“There are a lot of new entrants into the space. The death of SaaS and the disruption from AI has shifted capital into areas of deep tech, space, robotics, energy, and defense,” he said. “There’s folks deploying capital who aren’t experts in any one of those sectors. So, consequently, we can talk about a bubble.”
The money has arrived fast. Venture capitalists put a record $37.9 billion into defense tech across 269 deals in the third quarter of 2026, up 117.5% from the prior quarter, according to PitchBook data cited by Fortune in its coverage of defense tech CEOs at the forum. Valuations have climbed with it: Early-stage defense startups have fetched 17 to 50 times revenue, Fortune reported this summer.
Even the sector’s biggest winners are uneasy. Anduril cofounder Trae Stephens told Fortune in June that mid-stage defense startups trade at multiples that are “completely disconnected from reality.”
Aidan Madigan-Curtis, a partner at venture firm Eclipse, described the mood bluntly.
“There is a pretty big YOLO sentiment happening right now, essentially in physical tech investing,” Madigan-Curtis said. “There are a lot of tourist investors who are excited about a person, a background, a theme… [and] maybe they’re most excited about who invested in the last round and the signal that that gives, versus a hardcore underwriting of a real set of capabilities that can truly pierce into a market.”
An Nvidia-sized jolt to private markets
That froth now meets a broader shock. Jensen Huang’s abrupt resignation as Nvidia CEO on Nov. 12, under pressure from the chipmaker’s board, has left the startup ecosystem primed for change and possible disruption.
AI startups are most exposed, but private capital markets more broadly are in flux, including the deep-tech bets now crowding into defense.
For startups, the harder test is selling to the government. It has long been a difficult market to crack, and the Pentagon, which has used the name Department of War as a secondary title since a 2025 executive order, is among the hardest. Part of the trouble is that government isn’t a monolithic customer, even if it looks like one.
“There’s a misconception that the Pentagon is this all-or-nothing type of customer,” said Faltas. “It’s actually not. The building itself is… called the Pentagon. It’s got five corners, and each of those five corners needs to be engaged with, and educated with, and listened to… That requires a very focused ground game.”