Peter Oppenheimer, Goldman Sachs’ chief global equity strategist, told clients in early August that technology stocks might not have a valuation problem. Instead, they might have an earnings problem. In a note published Thursday, he came back with the receipts.
The new report, titled “Competition for Capital,” doesn’t back off the August thesis. It hardens it, tying the risk of an AI-driven “earnings bubble” to a specific mechanism, a specific historical stress test, and a specific near-term trigger that he says is already showing up in this month’s bond-market turbulence. He still won’t say that this bubble definitely exists. But six weeks after first raising the possibility, the hedge is now backed by capex-to-cash-flow data, record credit issuance, and a downgraded near-term outlook on stocks.
The August admission
In early August, Oppenheimer wrote that “there does not appear to be a valuation bubble, but there may be an earnings bubble” building in technology stocks—a notable concession from a strategist at what one of the Street’s most consistently bullish research shops.
At the time, Oppenheimer’s evidence was mostly anecdotal. He pointed to the wild swings in that quarter’s earnings, Microsoft’s stock jumping 17% in a single day on strong earnings, Meta shares falling nearly 10% despite beating estimates, and the equal-weighted S&P 500 outperforming its cap-weighted counterpart by the widest margin since 2009—signs, in his reading, that investors were growing suspicious of how concentrated the earnings growth powering the market actually was. He linked the risk loosely to “more government debt, increased issuance, and persistent inflation” pushing up the cost of capital, without fully spelling out how that connected back to tech earnings specifically.
Thursday’s note turns that loose linkage into the central argument. Oppenheimer now says AI infrastructure spending and government borrowing are directly competing for the same pool of capital: private companies raising debt and equity to fund AI data centers, at the same time governments are borrowing more for infrastructure, energy security and defense, all while inflation from higher energy prices pushes policy rates higher too. That collision, he argues, is what’s driving up the global cost of capital—the mechanism that was only implied in August is now the report’s title and its through-line.
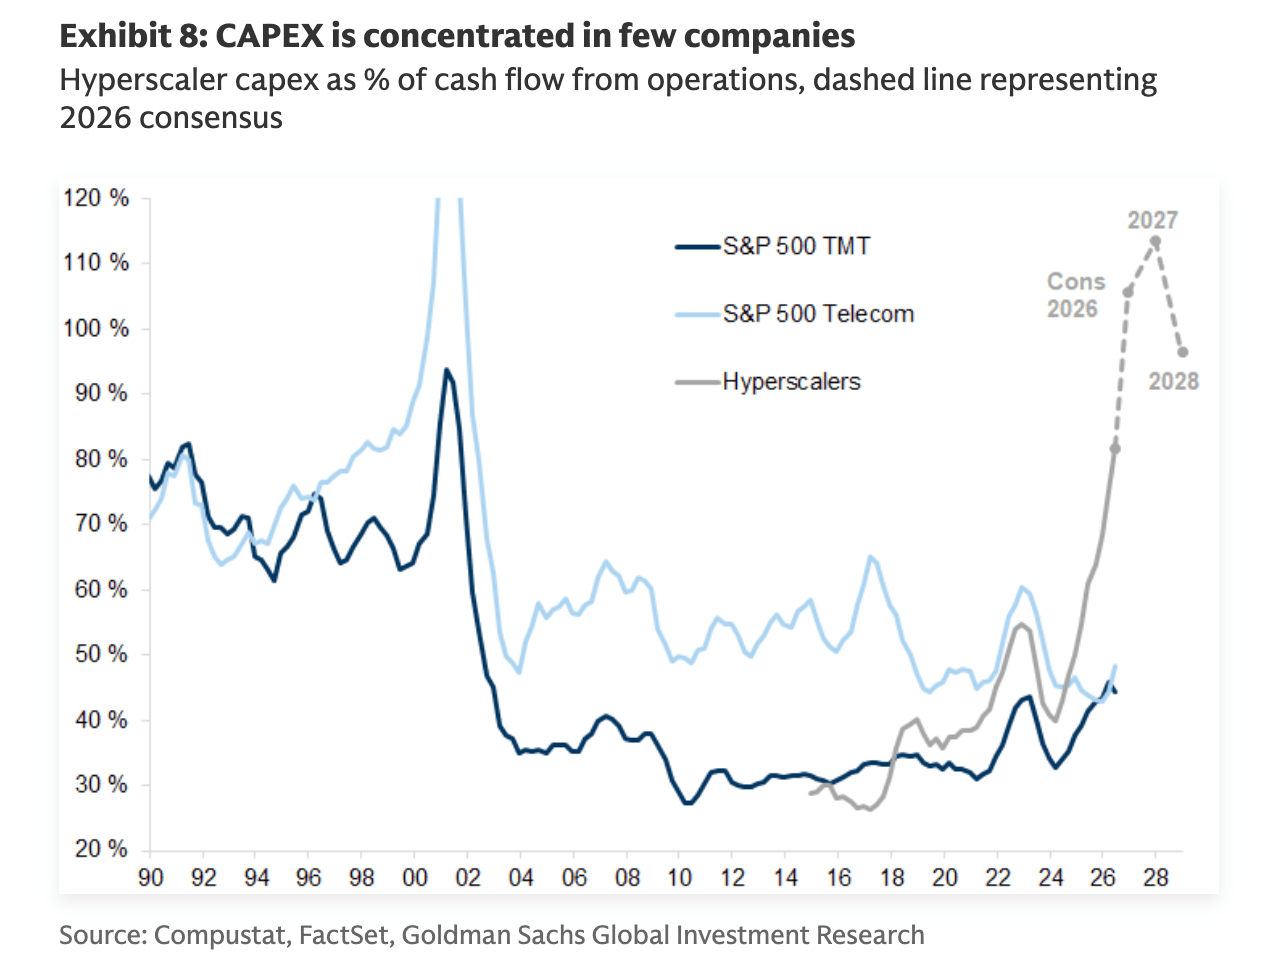
He backs the argument with sharper numbers: Capital spending among AA-rated technology issuers grew 65% year-over-year in the second quarter, marking the tenth consecutive quarter that aggregate AA capex growth has topped 35%. U.S. convertible bond issuance has reached $135 billion year-to-date, with AI-related borrowers responsible for 44% of total volume. And Goldman’s credit team raised its full-year U.S. investment-grade issuance forecast by $200 billion, to a record $2.3 trillion, with AI-related issuers now accounting for a quarter of all that supply.
An independent echo from Apollo
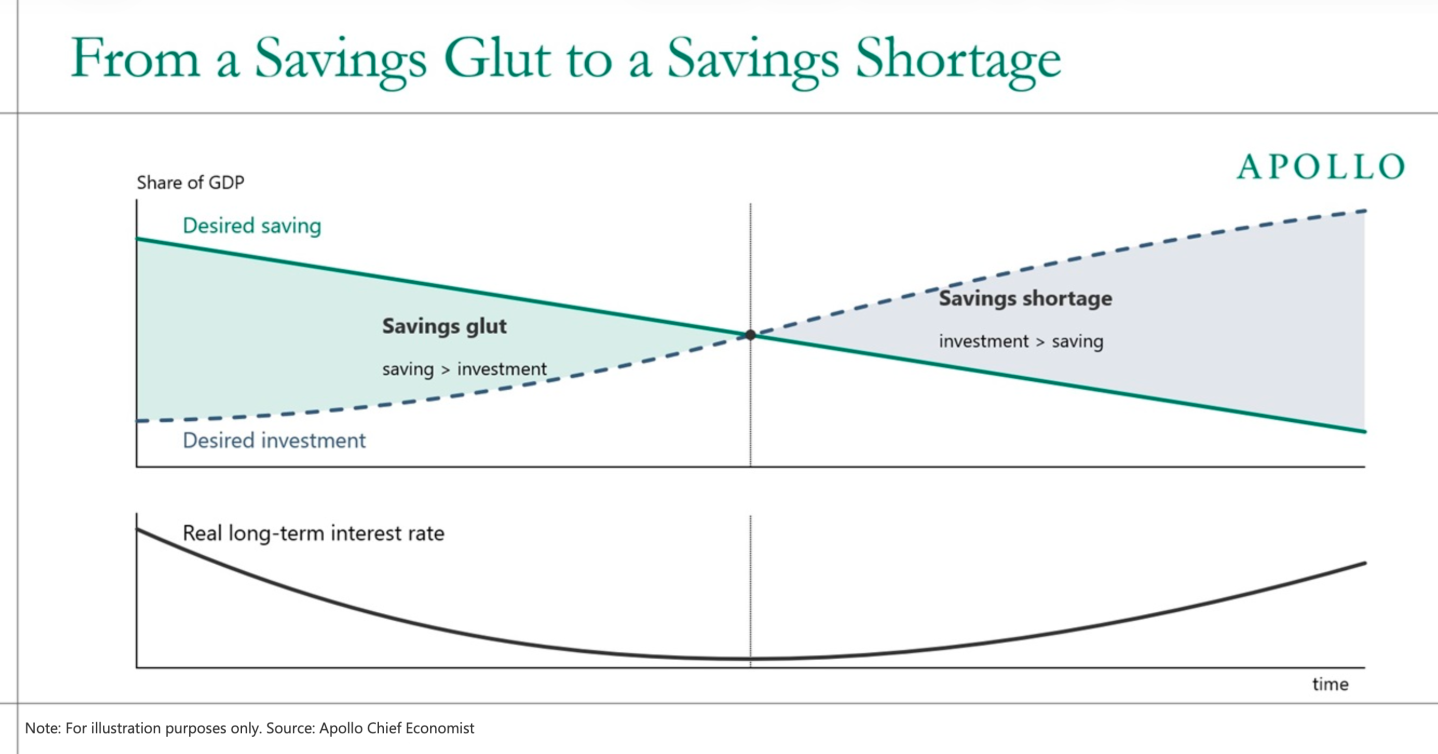
Oppenheimer isn’t the only senior Wall Street voice converging on this framing. Five days before his note was published, Torsten Slok, chief economist at Apollo Global Management, wrote his own diagnosis, arguing that what used to be a “savings glut” has turned into a “savings shortage.
Slok argued that the two-decade regime of ultra-low rates was a function of excess savings chasing too few investment opportunities. “That has now changed,” he wrote. “Today, there are more projects than capital … When projects are abundant and capital is scarce, capital competes for projects, and it competes by demanding a higher return. The return that clears the market is a higher yield.” He offered a rather cute doodle to make his point.
Slok’s evidence is already visible in secondary bond markets rather than merely forecast, as he pointed out that spreads on hyperscalers’ longest-dated bonds have widened, and that “most of the paper issued in 2026 trades wider today than where it priced. Investors are still buying. They are just charging more.”
He also offered a precise explanation for why long-term rates specifically have moved more than short-term ones—a dynamic Oppenheimer’s own note opens with, citing 30-year German and Japanese yields near zero as recently as 2022. “Data centers, power generation, transmission and government deficits are all long-duration claims on savings,” Slok wrote. “So the competition for capital concentrates at the long end of the curve, which is why long rates have moved more than short rates.”
Running the 2008 comparison to its conclusion
Oppenheimer’s August note gestured at historical parallels without fully working through them—pointing to 2008 banks, the dot-com bubble of the late 1990s, and Japan’s bubble in the late 1980s as prior instances where earnings, rather than valuations, blew up first.
He notes that banks briefly became the largest sector in the S&P 500 in the run-up to the 2008 financial crisis without ever trading at extreme valuations the way tech did in 1999 or Japanese stocks did in the 1980s. Instead, bank earnings were inflated by rapidly rising leverage financing an asset that did experience a genuine valuation bubble: U.S. real estate. When housing collapsed and pushed the economy into recession, bank earnings collapsed with it, even though the stocks themselves had never looked obviously overvalued.
He then checks technology against that same model and lists three reasons he thinks today looks different. First, technology profits remain “very robust” and balance sheets are “strong overall,” a contrast with the credit-fueled fragility that eventually undid bank earnings. Second, interest coverage ratios for the aggregate S&P 500 rank in the 99th percentile of the past 20 years, and the median stock’s coverage ratio ranks in the 68th percentile—evidence, he argues, that companies broadly are not over-leveraged the way banks were. Third, demand for AI compute is “accelerating and outstripping supply” rather than sitting atop an asset that’s already inflated, pointing to Microsoft’s stated plan to triple its data center capacity within six years and to Nvidia’s reiterated forecast, delivered at Goldman’s own Communacopia Technology Conference, that the AI total addressable market will reach $3 trillion to $4 trillion by 2030.
Still, this isn’t a clean bill of health. Oppenheimer wrote: “Any slowdown in profit growth, in an environment of a much higher cost of capital, could put downward pressure on equity prices, reducing confidence in future cash flows across the ecosystem from the hyperscalers to the ‘pick and shovels’ that have been benefiting from the capex boom.”
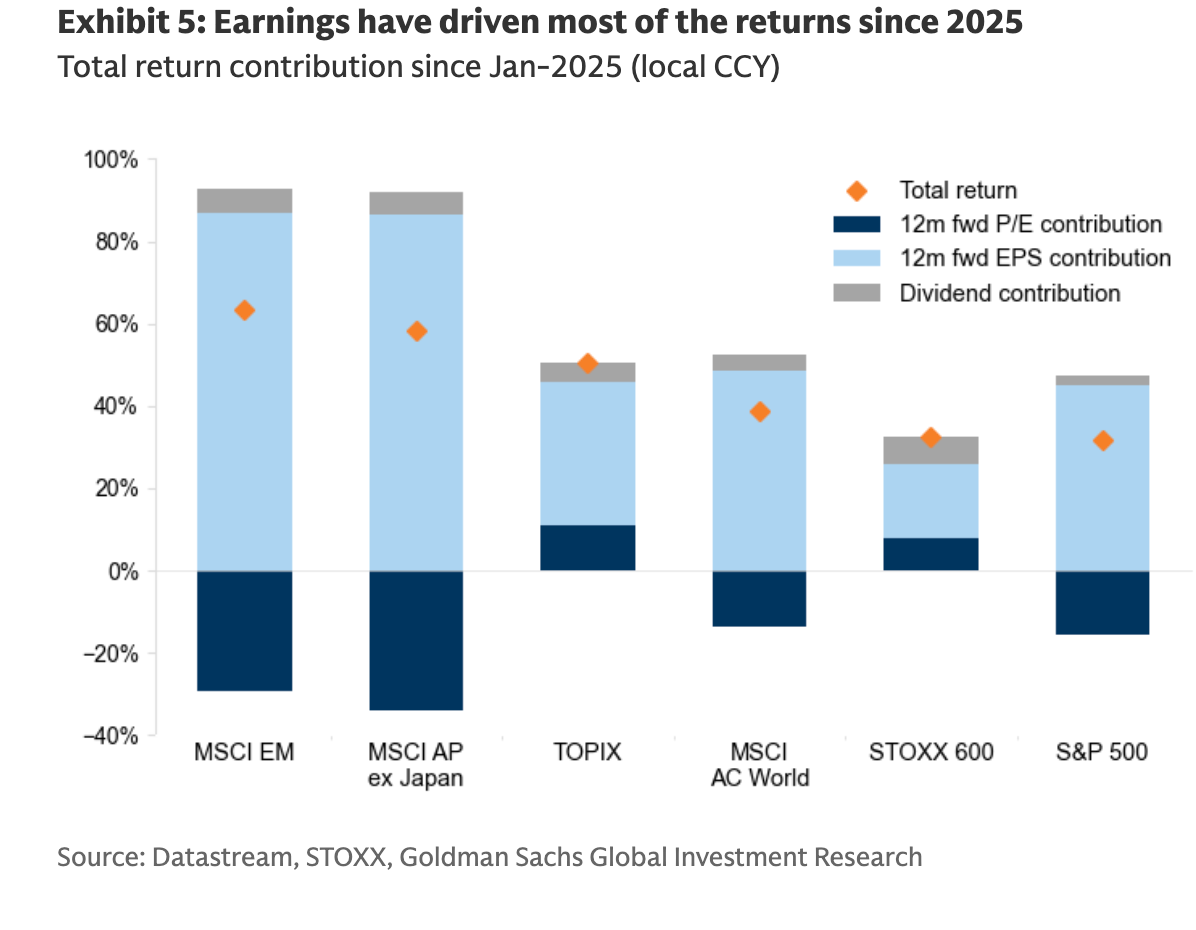
Investors got a preview of what that tension looks like in practice just three days before Oppenheimer’s note was published. On September 14, Nvidia fell more than 3% and other chipmakers dropped between 5% and 6%, dragging the Philadelphia Semiconductor Index down almost 6%, after Anthropic CEO Dario Amodei called for a slowdown in frontier AI development over safety concerns, a call quickly echoed by OpenAI’s Sam Altman. Yet Alphabet, Microsoft and Meta—the hyperscalers actually funding the buildout—rose on the same day. Gil Luria, head of technology research at D.A. Davidson, told Fortune the divergence reflected the asymmetry that if AI progress slows, the hyperscalers can simply stop adding data center capacity and “harvest returns” from what they’ve already built, while the companies selling them chips and infrastructure have no such option.
For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.